CaptainFIs financial and personal update for Q3 2026
Captain FI is not a financial advisor, does not hold an AFSL and this article is not financial advice. This website is reader-supported, which means we may be paid when you visit links to partner or featured sites, or by advertising on the site. For more information please read my Privacy Policy, Terms of Use, and Financial Disclaimer
Executive Summary
Our household net wealth has grown to $2,806,587, an increase of $78,100 since our last update in Q1 2026. This quarter has been about building a more sustainable lifestyle, investing in our hobby farm, and making progress towards our long-term financial goals while enjoying life with our growing family.
We’ve completed a major solar and battery upgrade, installed additional farm infrastructure, expanded our Dorper sheep flock and invested into expanding our apiary (bees). These projects require significant upfront spending, but our aim is to reduce ongoing living costs, produce more of our own food and gradually build additional income streams.
Financially, our principal residence valuation increased to approximately $2.815 million, while our investment property valuation fell to around $804,000. We have also redrawn against our home loan to fund our solar installation, leaving a net mortgage position of approximately $520,000 on our principal residence. Our investment property remains negatively geared, so we’re continuing to assess whether holding it long term or eventually selling it to reduce our home loan will best support our family’s goals.
Our estimated baseline living costs are around $70,000 per year, with a longer-term spending target of approximately $85,000 annually. Keeping our expenses manageable gives us greater flexibility to reinvest in our businesses, pay down debt and spend more time with family.
I’m also deliberately slowing down my blogging and business activities to focus on what matters most: raising our family, enjoying life on the farm and building a lifestyle that doesn’t require us to maximise our income or spend every waking hour working.
Financial independence isn’t just about accumulating the biggest possible portfolio. For us, it’s about having the freedom to choose how we spend our time, provide for our children and enjoy the life we’ve worked hard to build.
Captain FI’s personal update
As is always the case looking back the year has seemed to rocket past. What has been amazing though is to see we are really moving in the right direction, both as a family and individually, and as a business on the hobby farm. We have deliberately slowed down, and are enjoying the process.
We have started doing our Gratitude’s before each meal, where we go around the table and verbalise what we are grateful for today. It has been a great way to slow down, and realise just how well we have it. We have also been working to really cut out the negativity and complaining, to the point where we will even ‘Nip it in the bud’ when we notice others begin to complain as it is contiguous and can result in the conversation having a downward complainypants spiral – we redirect this by subtly pointing out how amazing life is and what we are grateful for in that moment.
We are actually so grateful to have developed such beautiful relationships here, we truly do feel like we have settled in paradise, and have some amazing people in our lives.
We have been paying for a bit of extra help around the property when it comes to projects, as well as stuff like gardening / weeding, house cleaning, pool cleaning. Whilst I could potentially be doing all this stuff ourselves, it has been great to just have those extra helping hands which also really helps with the mental load / burden of running such a large property and home. It has also meant we were able to spend more quality of time with my mother in law who has been staying with us for the past year, and who is currently travelling through China and other parts of Asia for a few months and then will be joining us back home shortly before the arrival of our next baby.
We have had some lovely friends and family visit this year from overseas and interstate, and it has been great to have such a large house that everyone can have their own room and space to breathe, and the 8 seater carnival has made airport runs and family outings effortless. Having two cars is an absolute luxury, but its meant I can take the boat out fishing whilst my wife still has transport if she wants to go out or in case of emergency, and also when we have guests we can offer them to borrow our car if they want to get around without spending an arm and a leg on a rental.
We have completed some major works on the property, including replacing our aging (and underperforming) old 7kW solar system with a new top-of-the-line sigen system (36kW panels, 20kW inverter, 50 kWh battery, Home Gateway, EV charger and whole home backup).
We have finally finished our back paddock and holding yard fencing, and grown our hobby farm with the addition of a small flock of Dorper sheep which we intend to grow to about a dozen sheep, to breed and supply our family with meat and potentially sell excess lambs. Whilst it was expensive setting up the infrastructure like fencing, gates, watering troughs etc, as well as the consumable stuff like vaccines, drench, vitamin blocks etc, this should pay itself off within the first couple of years. We are excited to finally be making great use of the space, and hopefully this means we don’t have to mow the paddock any more, which saves a lot of time and diesel fuel (which is getting expensive). Also pretty keen for our food forest trees to grow a bit bigger and tougher so we can run some lambs in there to keep the molasses grass down so I don’t have to whipper snip and mow as much there, too. This is also great so we can ‘rest’ the other paddock, however we think if we let them go in there now they will probably just destroy some of the younger trees, so I have got some work making some wire circle tree guards with our left over fencing wire.
I still need to build a small shelter shed / barn and holding pen down there to make things easier with lambing and drenching etc.
We have also wholesale purchased a significant number of native bee hives in to help bring in some new genetics to our native bee apiary which I am lead to believe makes them more resilient to pests and diseases. To cover these costs I have sold quite a few of our existing bee hives (both honey bees and natives) as well as completed our first crop pollination contract – it was a lot of fun, but also really hard work. Loading and unloading the hives really took a toll on my body, so I don’t think we will be deliberately seeking pollination contracts going forward, and just sticking to breeding bees to sell and for the honey (although the honey is a lot of work too). I sold the farmer 4 beehives after the pollination contract ended (which was helpful as less to bring back) and he is paying me for lessons to teach him how to keep bees and breed them into more hives so he can be self sufficient in the future and not need to bring bees in – which means we might still do their Summer 2026 contract for lychees, but possibly not the next Spring 2027 for Avocados.
We are experimenting with our first batch of chicks, in the absence of a rooster (sensitive next door neighbour!) we have purchased 4 dozen fertile eggs as we had 4 of our laying hens go clucky – by giving them a clutch of eggs to incubate for the month, they seem pretty happy, and soon we should start to see them hatching. We haven’t done it before, so excited to see what happens.
We haven’t lost any fruit trees this year which is good, and I have also added in some new types of fruit trees such as a couple varieties of custard apples / cherimoyas, a few dozen passion fruits, and planted out a few varieties of strawberries. I am kicking myself for not putting in coconut palms when we first moved in, and that’s top of my priority list is to get about two dozen dwarf malay coconuts planted throughout the property. My wife is pregnant with our second (not long to go now!) and she could down at least 5 coconuts a day without breaking a sweat, so this is a worthy investment for the future. We have struggled with avocados and phytophthora, but I am going to give it one more crack and put in another two dozen avocados which I will be treating with phosphoric acid fungicide fairly regularly over the first few years to see if we can get them going. We eat LOADS of avocados so if we can become self sufficient in these, it will literally save us over a thousand dollars a year.
I have finished re-vamping our raised garden beds / herb beds, and since we were doing the sheep fencing, I finally fenced off the veggie area and put in gates, which is helpful to keep the property in ‘permaculture zones’ and manage animal access. We still do need to terrace the veggie beds properly, as there’s a decent slope and I initially just did a very cheap and rough job in ‘hügelkultur’ style when we first moved in using wooden logs held in place by star pickets to make rudimentary retaining ‘mounds’, but since this is 3 years old most of them have rotted out now. I actually need to get in some concrete sleepers and H posts and properly concrete them all in, they only need to be probably 2 sleepers high but its still a massive job and one that I will probably defer till next winter at least. I am still getting over our last retaining wall project which we had to put in in preparation for the shed (Shed build is on the back burner currently until I earn a bit more $$$).
I was pretty shocked when we ordered a 10 cube tipper truck full of 20mm drainage gravel aggregate / blue stone which we use for all the footpaths and driveways / parking around the property. It ended up being $1500 delivered, which I thought was just fucking insane for rocks. Anyway that’s kept me busy (and fit) carting that around and topping up pathways. We have actually also been bringing in a gardener / labourer for a bit of extra help once a week around the property and this is a job I was fairly happy to palm off to him 🤣🤣
Another small project I have worked on was my mate and I welded up a cage for my old box trailer, got a canvas cover done up for it, changed the wheel bearings and gave it a wire brush / sand, a rust etch, prime and a few layers of paint – so I now have a fantastic trailer for transporting livestock (mostly beehives and sheep) which should be good to go for another decade or hopefully longer (I can’t believe I have actually had it for 16 years already)
Solar system Upgrade
After all the horror stories we heard about electricians refusing to upgrade “older” systems (as in only 5+ years old) we decided in the end to just over engineer our system for the life cycle requirement (25+ years) over our current requirements.
It does mean its a bit of overkill for now, and on sunny days we export about half our production (around 85kWh) but once we have a few more kids, get an EV and the spa, sauna and pool heater, that excess production will be gobbled up and a Smart-Box will prioritise consumption – charging our home battery first, and then the (future) EV, and then max out our home air con, pool heater and spa as a makeshift “thermal battery” before exporting to the grid. We currently have a solahart hot water heater (and an instant gas home water heater backup) which don’t use much power at all, but when these need replacing we will replace them with a pair of large heat pump hot water tanks, and these will also be a large ‘thermal batteries’ where we can store excess midday solar energy we generate.
We initially got a dozen quotes from a range of local (and a few interstate) installers, we gave them all the same requirements briefing and the quotes came in from around $30,000 for the poverty spec brands, up to $108,000 for Sigen, for roughly similar sized systems (but with varying levels of price gouging).
I am in the process of doing up a fairly comprehensive article about it all, but the long and short is that Trev and Stephan from Just Better Energy worked with us over about a year to analyse our situation, critique other quotes and design a future proof system, and once we were ready to go ahead they hooked us up with a great system at a great price. They weren’t the cheapest (going by price alone is a bad idea as lots of cowboys out there), but they were competitive for the Sigenergy brand, incredibly good value for what we got in terms of the complex install, and the customer service and after sales support has been exceptional.
It’s worth mentioning that everyone’s install is different (different requirements, layout, cabling, roof aspect, panel / inverter / battery sizing etc) so you can’t just expect to get the same price as what someone else paid (even for the same size system), but for what it’s worth our final cost was $41k, which was 4 strings (East, North, North and North-West) with internal firewall penetrations and re certification, battery and sub board on the opposite side of the house to the main switchboard (big fat cabling = $$$), whole home backup etc. For comparison, Trev also put in a system for our next door neighbour but it was a much simpler install (just one large north facing “cookie cutter” install) and a smaller system with a cheaper brand for approx $20k (I think this was approx 20kW panels, 10kW inverter and 30kWh battery).
Like any large project, there was always going to be some teething issues and this one was no exception. We had a few minor issues on the install with a big crew working two days, and commissioning troubles due to a faulty wifi communications module in the Sigen inverter – it was frustrating after seeing all the hard work of the crew and such massive infrastructure all go in, but then not have the system work due to a technical issue – but I am glad to say in the end everything was resolved. During the process Sigen actually delivered a replacement inverter which thankfully in the end wasn’t needed as their technicians were able to identify the issue – we ended up doing an NBN upgrade to the property, and reconfiguring the wifi mesh with a big network and additional nodes – in the end. the system is operational and working better than expected!
We haven’t had a bill since, and actually earned a couple hundred bucks in credits from our excess solar feed in – which covers our daily supply charges, plus our LPG tanks for hot water heater backup, and even the internet bills. Combined with being on rain water tanks, and our own septic system makes us “utility cost neutral” which is kinda cool and makes us feel more self sufficient.
We calculated that the system will pay itself off in under 6 years, and so was a better investment than simply paying down our mortgage. After that point, I guess its ‘free’ electricity, and that $6k a year saving then is for life and helps offset other fixed costs we can’t avoid such as council rates, home insurance and car rego and Insurance. The other final point is that electricity costs seem to just continue to skyrocket, and our previous $1500 quarterly bill would just grow and grow each year with inflation. With this large solar system, we are now out of the game of buying electricity. The only catch is eventually we may have to replace the battery which can be expensive!
Financially, we aren’t really sure how we ‘keep track’ of this investment, so we are kind of writing it off in our heads as a renovation expense on the property. Our real estate agent said that every $1 dollar you invest into solar brings back $2 dollars on a sale price, which I guess is probably true of most renovations. He also said the same thing about our plans for the BFS (Big F Shed). Since we aren’t planning to sell any time soon, we are just treating it like the money has disappeared 🤣 In reality though, this is significantly reducing our cost of living, so it hasn’t really.
Whilst we do have to pay a little bit of interest on the amount we redrew (around $3K annually), we are now saving over $6K a year by not having electricity bills – plus we now have blackout protection – which lets us work online uninterrupted, live a more bougie lifestyle with aircon, and we aren’t at risk of losing thousands of dollars worth of meat in the chest freezers etc. The meagre amount we earn from selling back to the grid covers our other utilities expenses.
Captain FI podcasts
I haven’t recorded any lately.
Overall I don’t think we will ever see a high publishing tempo Captain FI podcast again, so they will more just be sporadic when I find a topic I find interesting or there is value to share in a discussion.
There is only so many ways to say “spend less and invest the difference” and “diversified low cost index fund ETFs” etc, and only so many people I am interested to track down and interview – after that it sort of gets a bit tiresome and constantly rehashing topics for content without really giving value to the listeners / readers – same kind of thing on social media / youtube channels I guess! I don’t know how some content creators manage to keep doing it, but I guess if its their full time job and they need the money then there is your incentive and they make it work!
Check out the previous episodes of the Financial Independence Podcast on Spotify or now they have been uploaded to the CaptainFI YouTube channel!
Captain FI blog articles
I have been slowing down with the blogging while we prioritise life with a young family on the farm. I am working on a post about our solar system though, and a review of Trev from Just better energy.
Captain FI 2025 spending figures
As I have talked about in my last few updates, my spending has increased a lot since we bought acreage and started our family. For contex over the past few years, my total spending figures (cost of living) were roughly;
- 2019 – $25k – Renting a subsidised Sydney apartment (single), working full-time and non-tax/resident for half the year.
- 2020 – $30k – Renting subsidised Sydney apartment (single), working full time with lots of away trips
- 2021 – $43k – Renting subsidised Sydney apartment (single), then moved to Adelaide
- 2022 – $32k – Renting apartment 6 months, then moved back in with my Mum as her carer
- 2023 – $69k – Renting a small house with my girlfriend (our combined total household spending figure inc holidays)
- 2024 – $144k – Moved onto acreage with my wife (large expenses furnishing house, farm projects etc)
- 2025 – $119K – Projects around the property (fencing + landscaping), wifes new car, 2 x overseas trips, 2 x domestic trips
- 2026 – $110k – So far for 2026: Mortgage, renovations, fencing + landscaping projects, stock, animals, property maintenance, solar panels etc. Estimating $130k for 2026
Our baseline cost of living estimate is around $70k per year (mortgage, groceries, rates, insurance, transport, health etc), and we seem to average around $15k a year on holidays and recreation. This figure always changes around because it isn’t a budget and doesn’t dictate our spending – it’s just what we seem to spend around, and works for us. In addition to that I have been spending money on farm projects and upgrades, which I am considering ‘one off expenses’ (that should end up making us money in the long run) and I dont factor those projects into the projected cost of living.
Going forward I’m estimating around a $85k annual spending figure, which is good because it means we only really need to generate around $8k a month income to cash-flow our baseline living costs after tax. This means any surplus we can put back into the business, shares or property upgrades (such as expanding the apiary, stock, fences, shedding and equipment).
Captain FI’s Investments
I don’t calculate a Net Wealth or Savings Rate Figure each month anymore, but I do try to keep a rough track of everything for these quarterly updates
My investments are split across the following areas;
The ‘FIRE’ Portfolio of Index ETFs(SOLD December 2023 to fund dream home).- Global shares – Betashares diversified high growth ETF (ASX:DHHF)
- Acreage – hobby farm in Queensland.
- Investment Property in New South Wales – Residential duplex
- My company – which runs a portfolio of content marketing websites
- Angel Investment in the investing platform Pearler
- Cash (Emergency Fund in the mortgage offset account)
NB – December 2023 I sold the ‘FIRE’ Portfolio (mix of Index ETFs) to fund my dream acreage purchase. In July 2025 I have started rebuying shares using the Betashares DHHF Diversified high growth ETF as the I believe the convenience of having an ‘all-in-one’ fund that is Australian domiciled for a tiny management fee of 0.19% is worth it for us.
My wife tracks her own investments separately and her investments include;
- Global Shares – Betashares diversified high growth ETF (ASX:DHHF)
- Global shares index fund via her superannuation
- Cash (emergency fund)
- Shares in several family businesses including a hospital, aged care facility and school.
The ‘FIRE’ Portfolio (Exchange Traded Index Funds) – SOLD
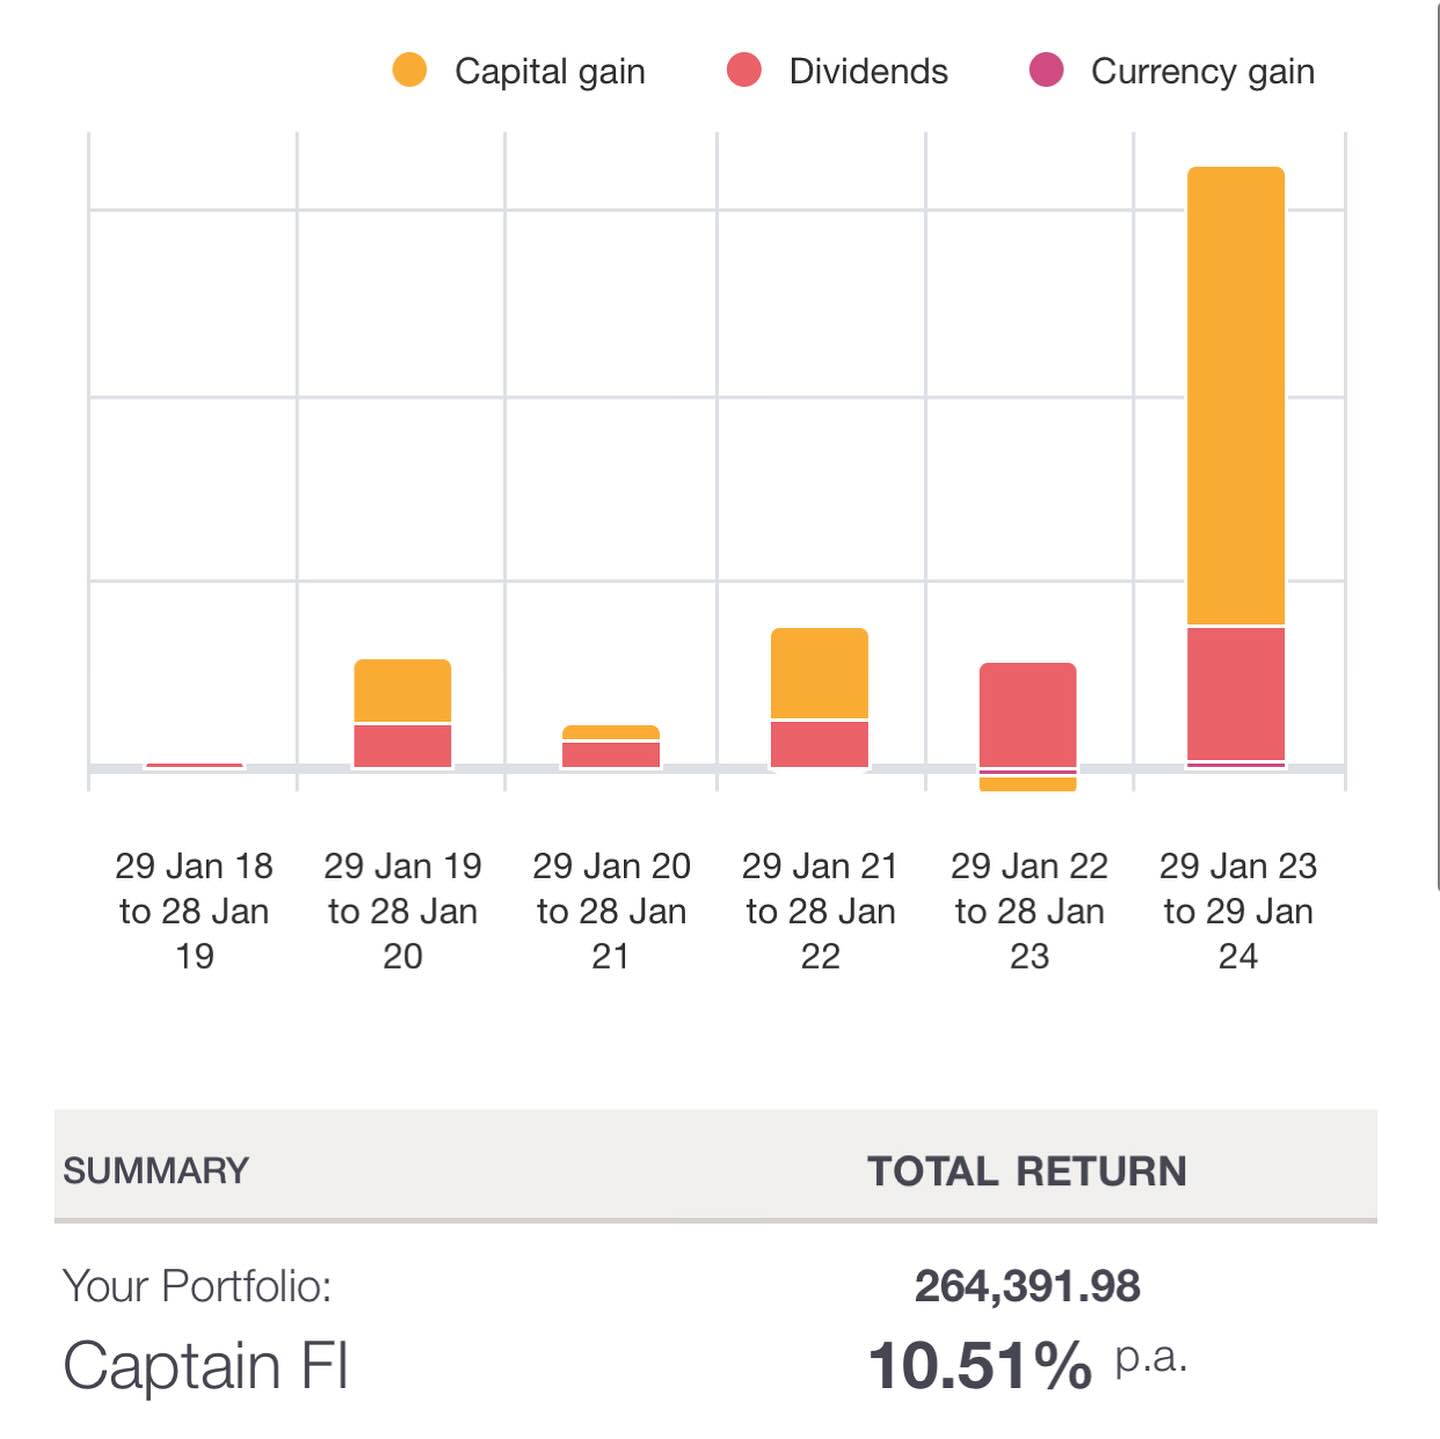
The ‘Financial Independence Retire Early’ or FIRE Portfolio was a simple, passive share portfolio started in January 2018 with the aim of growing wealth through both capital gains and tax efficient franked dividend income.
It was split between three parcels of incredibly low-fee, index-tracking Exchanged Traded Index Funds (ETFs) to achieve global share market diversification – A200 (15%), VTS (60%) and VEU (25%), and I tracked the share portfolio using Sharesight, which means my portfolio accounting and tax reports were all completely automated.
After six years of passive index fund investing where I bought shares every payday with the intent to live off dividends once I retired, I finally sold the entire portfolio in December 2023 so I could buy my forever home – a large luxury home on acreage in the SE QLD hinterland where I can hobby farm and raise my family in peace and quiet.
Cashing in the chips I sold approximately $1.7M of shares with a total profit of $264,391.98 or in other words an annualised return of 10.51% – which was an incredible feeling. Whilst it was difficult to let go of that passive income stream and the market has continued to grow since I sold, I had achieved what I set out to do which was to become financially independent, retire early from the rat race, and buy my dream acreage to raise a family.
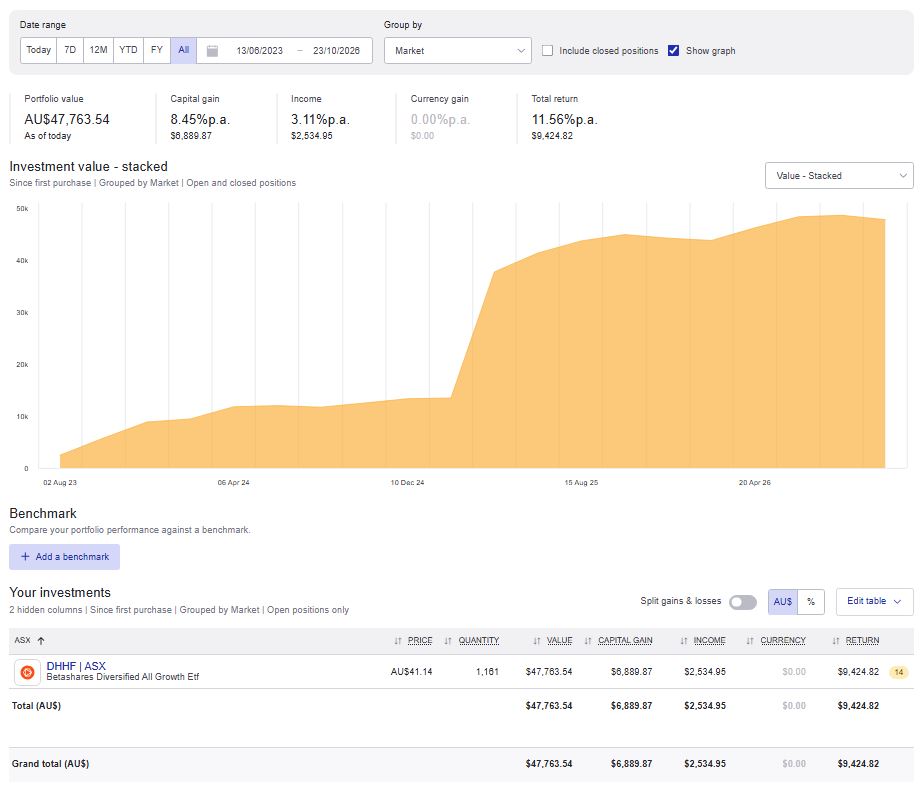
Back in July 2025 I started rebuying shares with a $5,000 purchase of DHHF. Whilst the priority at the moment is paying down the mortgage and reducing our cost of living, I still wanted to get the snowball started on rebuilding the share portfolio and increasing our passive income.
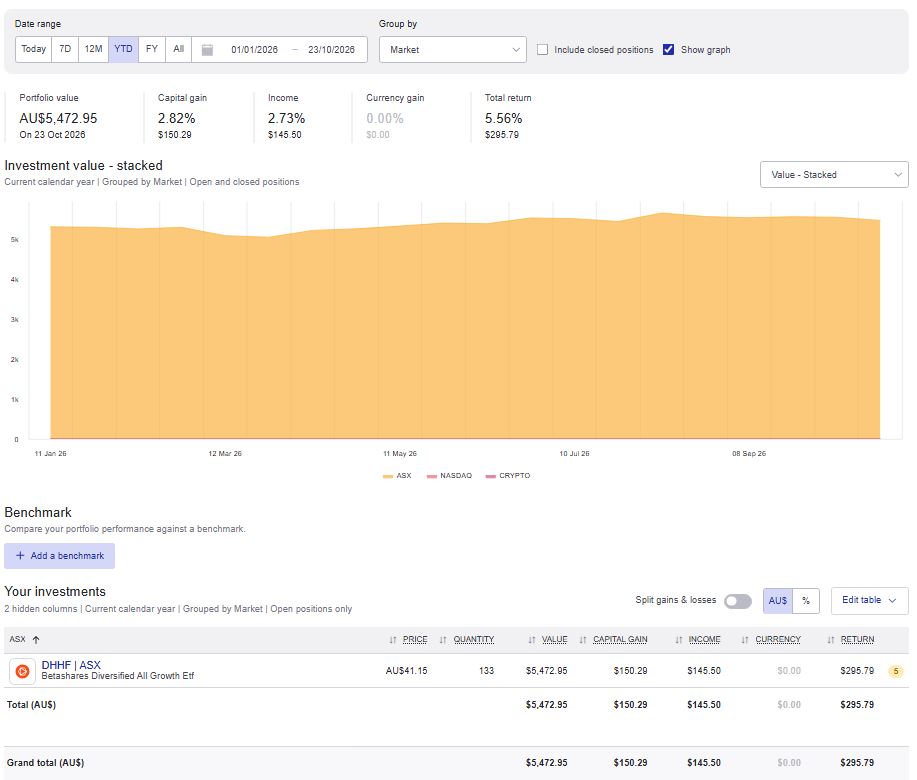
We decided it makes sense to also invest in my wifes name as well, which allows us to optimise the tax bill if we do ever need to sell off any parcels of shares as we can pick who ever is on the lowest tax bracket.
Captain FI’s Primary Place of Residence
The current PropTrack automated online valuation estimate is $2815K, which is up $105K from the last time I checked it for the Q1 2026 net wealth update.
Whilst we do want to pay off our mortgage, and traditionally this means the number should go down 😅, we did redraw from the mortgage to pay for the solar upgrade and so we are back up to owing $530K on the mortgage, with $10K in the mortgage offset account. The net mortgage position is $520K, of which I pay a ~$4000 monthly repayment.
We had an option for a ‘green loan’ at a lower interest rate than our mortgage, which technically would have been cheaper, but as the loan term was shorter, it actually meant we would be ‘worse-off’ cashflow wise, so we just ended up redrawing from the mortgage to keep it simple.
I mentioned earlier that we have treated the redraw for the solar upgrade as an ‘renovation’ expense rather than an investment – we are still just using the standard PropTrack automated valuation, but we are reasonably confident if we ever did need to sell, with all the capital works on the property we have done, we should easily exceed the online valuation estimate.
In previous updates I had mentioned we had plans to Debt Recycle on our home. After we crunched the numbers and spoke to our accountant, we discovered it’s not really worth it for us. We aren’t on high taxable income. Interestingly, doing the debt recycling would have made for great blogging as I could present lots of nice investing charts for my readers and potentially grow some new affiliates in that space, but realistically it wouldn’t be genuine as we personally want to focus on reducing our hobby farm non-tax deductible debt and our overall risk now that we have a young and growing family. So for now that just means smashing down the loan as quickly as possible (balanced against semi retirement and quality of life) and accepting that this is a bit of a slow and steady, boring process.
Hobby farms are an interesting kind of property, and having the space for the food forest, sheep, vegetable plots, chickens and apiary means that we can not only reduce our cost of living by producing our own food and swapping for things we need (eg we did a bulk honey for beef swap this year), but we can also earn money from our hobbies and I am really working toward expanding this – we had some great success this year with pollination contracts and bees, so my plan is to slowly build up these avenues to try to pay down the mortgage faster. Currently I have been ‘reinvesting’ pretty much everything into infrastructure, trees and stock, but once we reach a critical mass we would be able to start drawing from it.
Captain FI’s Investment property
The current PropTrack automated online valuation estimate is $804K, which is down $90k from the last updates estimate (labours negative gearing changes and higher interest rates?).
Our current mortgage has $523k remaining.
Its currently negatively geared and this property costs about $100 per week to hold. We do get a small amount back on tax so the actual overall net cost is probably closer to $75 a week at the moment. We are happy to take a small cash-flow loss for now as we believe longer term that property prices will go up, and as the rents go up with them over the next year or two this will eventually become cash flow positive.
We actually wanted to refinance to an interest only loan, as we see paying back principle to be locking up our money into equity we can’t actually access, but we didn’t have a high enough income to refinance, especially now we have kids and with interest rates going up.
One idea we had was that in a couple of years, if property prices keep going the way it has been going, we could probably sell the IP, take the capital gains tax hit, and then use the proceeds to pay off the mortgage on the hobby farm and throw any left overs into shares for more passive income.
With the political tinkering and interest rates going up, I’m predicting that its value is likely to go sideways for a couple years and not do much. At least we will be paying down the loan, and I do think rents will still increase with inflation (which is high at the moment), so it should become cash flow positive soon at least. We may have to hold it for around 5+ years before we see enough price growth to be able to use it as the hail mary option to pay off the hobby farm.
Another option is to hold it long term, use it as a source of income to live / travel etc, and only sell for example when we want to gift our kids money for a deposit for a home of their own.
I have previously written a full separate article on the IP build if you want to know more about the process – CaptainFI’s residential property development investment.
Captain FI’s Online Business (website portfolio)
I make money from this website and others through a content and affiliate marketing strategy. These make money semi-passively from display Advertising through managed ad networks such as Google Adsense and Mediavine, and affiliate programs such as Amazon Associates .
I’ve written a pretty detailed article here about how to make money online, and I recently published a few more articles about how to start making money online for beginners, as well as an ultimate list of blog income reports for anyone wanting a peek into the industry.
A while ago I decided to shift my strategy and just work on my bigger sites rather than trying to spread myself too thin across a massive portfolio of start ups. Right now my personal focus is on making as much money with as little effort as possible, so I can spend my time on the hobby farm with my family.
As a result, in the past couple of years I have sold off the majority of my content sites and if I am honest, I do feel better for it as my workload feels a lot more manageable and there are less ‘balls in the air’ to keep juggling.
I would never sell CaptainFI.com, there is just too much of me on this site. It’s like a personal diary and I love going back to read old updates and see how my philosophy has changed over the past decade as well as other personal development and goals that I have set and achieved. I don’t think I would ever sell my Aviation site either, nor the permaculture one, as I will be building them both out over the next few years as I want to get back into part time aviation instructing and contract work, and offering permaculture education, services and sales, so both of these sites will be transitioning into commercial service blogs.
I still have a couple for sale in the camping / van life and parenting niches if anyone is interested in giving this side hustle a go. You can check out this article on website operation if you are keen as I’ve listed all the details in there. Feel free to send me an email through the contact form or get in touch on social media if you are interested in getting started.
I originally learned these skills through the eBusiness institute over the past 7 years – I have done a pretty comprehensive review of the eBusiness institute as well as interviewed Matt and Liz Raad about this on the podcast a couple of times where we go over a huge list of frequently asked questions about online business if you want to learn more about this. They also provide some free introductory training for CaptainFI readers.
Check out these podcast episodes for more information
- Podcast | Q and A Session with Matt Raad – Part THREE
- Podcast | Q and A Session with Matt Raad – Part TWO
- Podcast | Q and A Session with Matt Raad – Part ONE
- Captain Fi Podcast | Online Business with Matt Raad
- Podcast | Digital Marketing with Richard
- Podcast | Entrepreneurship with Liz Raad
- Podcast | Digital entrepreneurs Matt and Liz Raad
I have also recently finished the Authority Hackers TASS (The Authority Site System) Course as well as the Making Sense of Affiliate Marketing course which has been a cool way to consolidate the skills I have learnt from the eBusiness Institute, and I have published a few comparison review articles such as Authority Hacker vs Making Sense of Affiliate Marketing and eBusiness Institute vs Authority Hacker which might help you choose between training providers.
Angel Investing
I made an ‘Angel Investment’ of $10,000 into the Fintech platform Pearler in 2020. Pearler was founded in 2018 and launched in 2020. Since then, Pearler has carved out a niche market in the financial independence community as one of the best investing platforms available. Since I made the investment the company has grown heaps, but there isn’t really a secondary market for these shares until Pearler either lists on the ASX or has a corporate buy out – so I can’t really get an updated official valuation till then. I still use them for my personal investing, and believe its a great company run by great people, so I’m happy to sit on it and see what happens!
Cash – Mojo Emergency fund
I currently have $10K cash in the offset as my emergency fund – we do want to build this up, so as to avoid having to redraw off the mortgage for unexpected expenses. Currently we have access to redraw a significant amount of equity through our mortgage which is why we aren’t all that stressed about building it up too quickly. The problem is when it does build up, its so tempting to purchase tools, stock or something cool for the property!
Captain FI’s Net Wealth progression
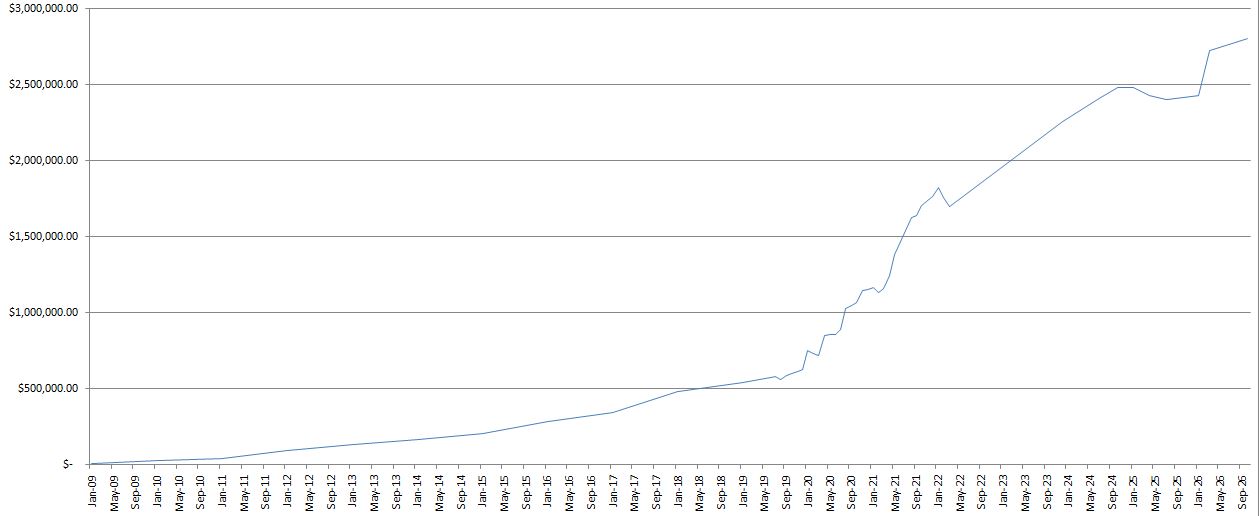
During my journey to FI I roughly documented my net wealth progression via monthly updates and a graph which was rather crudely constructed in Excel. It demonstrates the ‘somewhat exponential’ journey over my 14 year ‘working’ career.
It starts off slow and then really ramps up when I was working bloody hard to grow it as fast as I could – I was in hardcore FIRE / savings mode and funneling everything into investments, and you see compound interest start to take effect. And then once I FIRE’d, it tapers off a bit as income drops and I stop investing as much, but having appreciating assets (property, shares) keep the net wealth rising, while part time work on my business means money is still coming in and I don’t have to draw down.
You can access the archives for my Net Wealth updates here to see how it’s gone over time. Check out the graph and all the updates below to see how it has gone since the beginning.
When I FI/RE’d, I stopped putting out regular monthly net worth updates (which isn’t really healthy – it became an obsession), and aimed to put out quarterly or biannual blog and net wealth updates.
| Date | Net worth | Difference | Saving Rate | Notes | |
| Jan 09 | $5,000.00 | ? | Estimate NW based on historical Super, Bank statements and assets at the time | LINK | |
| Jan 10 | $24,000 | +$19,000 | ? | Estimate NW based on historical Super, Bank statements and assets at the time | LINK |
| Jan 11 | $40,000 | +$16,000 | ? | Estimate NW based on historical Super, Bank statements and assets at the time | LINK |
| Jan 12 | $92,000 | +$50,000 | ? | Estimate NW based on historical Super, Bank statements and assets at the time | LINK |
| Jan 13 | $130,000.00 | +$38,000 | ? | Estimate NWbased on historical Super, Bank statements and assets at the time | LINK |
| Jan 14 | $161,000.00 | +$31,000 | ? | Estimate NW based on historical Super, Bank statements and assets at the time | LINK |
| Jan 15 | $200,000.00 | +$39,000 | ? | Estimate NWbased on historical Super, Bank statements and assets at the time | LINK |
| Jan 16 | $281,000.00 | +$81,000 | ? | Estimate NWbased on historical Super, Bank statements and assets at the time | LINK |
| Jan 17 | $340,000.00 | +$59,000 | ? | Estimate NW based on historical Super, Bank statements and assets at the time | LINK |
| Jan 18 | $482,000.00 | +$142,000 | ? | Estimate NWbased on historical Super, Bank statements and assets at the time | LINK |
| Jan 19 | $542,000.00 | +$60,000 | ? | Estimate NWbased on historical Super, Bank statements and assets at the time | LINK |
| Jul 19 | $578,900.00 | +$36,900 | 84% | Finally began tracking NW this like a proper adult. | |
| Aug 19 | $560,100.00 | -$18,800.00 (-3.2%) | 78% | Share market slight correction, Ok savings. | |
| Sep 19 | $584,744.88 | $24,644.88 | 72% | Share market rebound, savings rate not so good. | LINK |
| Oct 19 | $600,386.00 | $15,641.12 | 84% | Good saving this month. Normal salary, plus allowances, dividends from index funds, tax refund, eBay selling and was working abroad in asia where things are cheap. | LINK |
| Nov 19 | $612,917.21 | $12,531.21 | 76% | Falling short of my savings goal of 80%. Mostly domestic legs this month with higher costs. Also invested in hydroponics. | LINK |
| Dec 19 | $625,350.00 | $12,432.79 | 76% | Good savings of cash (for development) and investment, however higher spending due to Christmas period (Travel and Gifting). | LINK |
| Jan 20 | $865,212.00 | $239,862.00 | 55% | Super settlement was a HUGE boost to NW. $9K growth from stock market. Expensive month lots with lots of unexpected bills – weddings, travel, Booking flights, fines etc. | LINK |
| Feb 20 | $851,802.0 | -$16,592 (-1.9%) | 52% | Large increase in spending on myself this month, still managed to tuck away $5K to put into shares and property. Corona Virus market scare resulted in a correction and gave NW a small negative trend. Time in the market not Timing the market! Became Single again. | LINK |
| Mar 20 | $819, 354.6 | -$31,806.95 (-3.7%) | 80% | Another small step backwards in the NW due to the ‘corona crash’ in full swing. FIRE Portfolio of ETF/LICs down about 15% this month, however due to high savings rate and structure of my superannuation annuity the NW is only down 3.7%. Savings rate good at 80%, higher than usual income (with some slightly higher spending, too). Picking up shares on discount – this is the best outcome for someone in the accumulation phase with good income! | LINK |
| Apr 20 | $847,023 | +$27,668 | 85% | $11,000 in rebound of stock market capital prices alone (up 6%), plus first quarter dividends paid (heavily reduced due to banks withholding dividends). Great savings rate due to COVID-19 lock-down = no spend. Increased entrepreneurial efforts and selling down of physical possessions provided side hustle income. Two standard paychecks from flying activity; domestic day trips only so no allowances. All cash unfortunately had to go into the property development due to contract timing, I am chomping at the bit to buy some more index funds before they go back up in price too much – hence why I am selling most of my toys! | LINK |
| May 20 | $857,859 | +$10,836 | 92% | Some Great sales as I let go of my Super Sport Motorcycle, Some gym gear, expensive flying equipment and a few other various bits and bobs and invested this money. Flying still reduced, but increasing from April. The share market grew as I continued to make my fortnightly investments. I also wrote down the ‘value’ of some of my possessions (liabilities) such as my car, tools and furniture by around $10K to align them to market price (“tell him hes dreaming…!”). | LINK |
| June 20 | $858,650 | +$791 | 90% | Small Net Worth gain as I continue to declutter and simplify my life, despite being off work due to a family emergency. Share market not doing much. | LINK |
| July 20 | $888,218 | +$29,568 | 68% | Majority gain due to share market going back up, low spending due to being on the family farm and at home because of lock down. | LINK |
| Aug 20 | $1,029,293 | +$141,075 | 74% | Became a millionaire. Achieved this massive milestone I set out for myself in Dec 2019. Included unrealised gains in my property development as well as website business. Good savings rate due to not much spending, invested in Aus and total world shares. Investing in my web business. Starting to shift focus away from $$$ and more into looking after my mental health. | LINK |
| Sep 20 | S1,045,486 | +$16,193 | 60% | Officially took time off work for the rest of the year to be close and look after family during major operations. Continued to sell down physical possessions and work on digital business while at home. NW gain mainly due to valuation of websites. | LINK |
| Oct 20 | $1,064,399 | +$18,913 | 80% | Base income (retainer) and leave loading, dividend and websites provided income, as well as raiding my P2P lending capital. Significant bill for property due to design not meeting standards which effectively lowers my equity position, as well as fence being stolen. | LINK |
| Nov 20 | $1,143,433 | +$80,394 | 82% | Big gains came from share market growth (influencing both the Financial Independence share portfolio and Invested superannuation), Business gains (due to increased earnings) and a $30K boost to my annuity thanks to me logging in and checking the fine-print on the accumulation stats. I only invested around $7K. Insane that in one month, I accumulated nearly more net worth than I did in four years from 2009-2012 | LINK |
| Dec 20 | $1,152,920 | + $9,487.32 | 84% | Share market slight drop, Earnings from Business, Contract work, Selling possessions. No share market investments this month (oops! I forgot and money was tight). Invested a lot into the website business this month (way more than planned) and it is still running at a decent loss (plans to turn it cash flow positive in 3 months). | LINK |
| Jan 21 | $1,165,678 | +$12,757 | 79% | Great returns from the share market. Earnings from Business, Dividends, Flying wage, flipping items on consignment. Regular share contribution, investing in micro investing platforms, P2P lending, Investment property and big reinvestment into the business (still running at a loss) | LINK |
| Feb 21 | $1,135,272 | -$30,406 | 76% | Significant write down on property development due to council DA rejection and redesign requiring more money and creating less equity. Offset by small increase to Business value and investments. Simplified my investments and switched over to Pearler. | LINK |
| Mar 21 | $1,155,594 | +$20,322 | 71% | Continued investment into the portfolio as well as growth of investments and business. Gave my notice at work and looking for part time job at home for ‘Barista FI’ | LINK |
| Apr 21 | $1,242,220 | +$86,727 | 74% | Property development back on track | LINK |
| May 21 | $1,379,469 | +$137,248 | 72% | Massive gains in the website portfolio due to revaluation based on recent business income, big growth of superannuation due to annuity increasing (salary increment) and shares generally went up. Crypto went down by about 40% or so. | LINK |
| June 21 | $1,469,989 | +$89,757 | 41% | Quit flying role and moved to Adelaide. Great month for investments, websites producing serious income so accordingly they are valued higher. Spent a lot on furnishing the new apartment and on enjoying some more luxuries. Seeing a therapist to help deal with anxiety from leaving work. | LINK |
| July 21 | $1,543,959 | +$74,732 | N.A. | Set myself up in Adelaide. Did basically nothing for the whole month except spent time with family, relax, sleep and go to doctors appointments. Massive boost to website portfolio AdSense and affiliate incomes, as well as general share market performance. | LINK |
| Aug 21 | $1,624,116 | +$70,156 | N.A. | Relaxed again, focused on mental and physical health, and spending time with family and my partner. Big increases to spending (too afraid to calculate a ‘savings rate’) but also big increases to NW through website portfolio income growth. Finally got the slab poured on the investment property (foundation). | LINK |
| Sep 21 | 1,640,663.85 | +$16,547 | N.A. | Stocks, super etc went down, but business income from websites increased, plus business valuation increased. Property build. got to frame stage, and I also got a dog! Expenses for vet surgery well worth it. Moved into a nicer apartment | LINK |
| Oct 21 | $1,705,907 | +$65,243 | 30% | Big boost from website valuation due to securing new affiliate contracts for recurring income, shares went up nicely. No massive changes to this month. Calculated a savings rate and found myself pretty low due to spending a lot on my garden and going out quite a lot – I don’t think I will calculate this savings rate figure any more. | LINK |
| Nov 21 | $1,739,144.23 | +$33,236 | – | Great month. Relaxing (somewhat). Spent a lot of money doing ‘fun’ things like winery tours, a fine dining experience and self education. Shares moved sideways (well slightly down) but everything else went up. Building got to enclosed stage (roof, walls, windows and doors) but have had some issues with build quality and weather / covid delays. Put a $1000 deposit on the puppy. Stopped tracking Savings Rate. | LINK |
| Dec 21 | $1,764,516 | +25,372 | – | Spent nearly the whole month with family, did some work on the website portfolio. Traffic recovered from google algorithm changes. Invested $10K into Stockspot and Sixpark, $1K into ACDC, $100 into Comsec pocket and $100 into Bamboo, $260 into BTC, $4K into ETFs through pearler. Paid the $3000 balance for the puppy. | LINK |
| Jan 22 | $1,826,633 | +$62,117 | – | Stock market slightly down, Massive boost to website traffic (overall its more than doubled). Invested $10K VTS, 2K VEU through pearler, Paid for Angels cancer surgery, bought more BTC and ETH, bought a parcel of ETHI on commsec pocket. | LINK |
| Feb 22 | $1,757,210.57 | -$69,422.93 | – | Stock market down, Website business revenues down and additional spending on content and staff for business, Additional property development bills, some unexpected expenses, Wrote down the value of some of my personal property (and gave stuff away). | LINK |
| Mar 22 | $1,701,410 | – $55,799 | – | My last ‘regular’ monthly Net wealth update as I give notice at work and finish up my non-flying job. | LINK |
| Q3, 2022 | Over $2M | N.A | – | Six months of Early Retirement in Rest mode! I stopped tracking my net wealth post-FI, my dog passed away, I gave away most of my physical stuff and moved to become my mums live-in carer, met a lovely girl, bought a puppy. Had some incredible months with semi-passive website income but overall neglected the business and regular (stable) revenues decreased. | LINK |
| Q1, 2023 | Over $2M | N.A | – | One year of Early Retirement! A lot of (sad) changes, the passing of my mother and family feuding resulting in temporary homelessness, selling my ‘nursery’ of plants, and traveling overseas for a few months. Finding a new home to settle, couple of domestic trips flying to Tasmania and Queensland a couple of times, and plenty of camping and road trips within SA. Did not work much on the business at all and lost a few more contracts and had to cut staff. | LINK |
| Q2, 2023 | Over $2M | N.A | – | Getting back on top of things with podcasting and blogging more regularly. Focusing on building our ‘rich life’ and deliberately increasing spending in areas such as food, travel and convenience. Did a few interviews and went on a few podcasts. | LINK: CaptainFI Q2, 2023 Net Wealth Update |
| Q3, 2023 | Over $2M | N.A | – | Big focus on health and fitness, fixing diet and losing excess weight. Continue to sell a few websites from portfolio and focus on largest ones. Attended some FIRE events and lots of road trips | LINK: Captain FI’s Q3, 2023 Net Wealth Update |
| December 2023 | $2.26M | N.A | +$260K (21 months since last calculated) | Interim calculation due to share sales prior to purchasing property – no update published | No update published |
| Q2, 2024 | $2,417,426 | 12% – Calculated to see where we sat | +$157,426 (6 months since last calculated) | Mid year 2024 Net Wealth update. Sold shares, crypto and 5 websites, Purchased the farm in Queensland, received $250K inheritance, significant cost in setting up the property. | LINK: Captain FI’s Q2, 2024 Net wealth update |
| Q3, 2024 | $2,485,000.00 | N.A | +$67,574.00 (3 months since last calculated) | Q3 2024 update. Lots of spending on wedding and bought a boat, preparing to debt recycle. Properties saw great paper gains. | LINK: Captain FI’s Q3, 2024 Net wealth update |
| Q1, 2025 | $2,482,000.00 | N.A | -$3,000 | Q1, 2025 update. Write down of business valuation due to reducing income. PPR valuation estimate down, IP up. Slowly paying off debt. Farm life is great! | LINK: Captain FI’s Q1 2025 Net wealth update |
| Q2, 2025 | $ 2,431,487.00 | N.A. | -$ 50,513.00 | Q2, 2025 update. Property prices up, continued to pay down debt, some big spending: household help, fencing, retaining walls and chicken enclosure projects, bought second car, paid for international trip and 3 x domestic trips. | LINK: Captain FI’s Q2 2025 Net wealth update |
| Q3, 2025 | $ 2,398,487.00 | N.A | -$ 33,000.00 | NW down again! third quarter in row… My father passed away. I have been spending time with family on the farm and raising our baby, our mother in law has been staying with us for six months. I have hardly done any (paid) work at all, mostly household / dad / hobby farm stuff. Got our flock of chickens and getting lots of “free” eggs… Made first shares investment for years (DHHF all in one fund). Property prices steady – switched back to monthly repayments to improve cash flow, bought some more upgrades for the farm. Paid the rates, rego (cars, trailers, boat), insurance, tax bills, and some BIG electricity bills ($$$!). Considering selling the investment property to pay down home loan and simplify finances. Probably should work more… | LINK: Captain FI’s Q3 2025 Net wealth update |
| Q4, 2025 | $2,433,746 | N.A | $35,259 | Property price valuations increased, driving NW higher. Fair bit of spending including pre paying $15K for two holidays in the new year, total spend for 2025 coming in at $119K, $44K above total yearly budget due to buying new car, tractor, farm projects and travel. | LINK: Captain FI’s Q4 2025 Net wealth update |
| Q1, 2026 | $2,743,487 | N.A | +$294,741 | Big growth in property prices, received approx $20K in paid parental leave, and growing business.. Sold some websites and old machinery. Also spent a lot in Tasmania, Japan and on annual vehicle and farm costs. Forgot to add boat, tractor, tools and furniture to NW tally previously so now included that which is why it seems abnormally high growth. | LINK: Captain FI’s Q1 2026 Net wealth update |
| Q3, 2026 | $ 2,806,587.00 | N.A | $78,100.00 | PPR went up, IP went down. Redid our Solar + battery, more sheep and bees on the farm. |

Captain FI is a Retired Pilot who lives in Adelaide, South Australia. He is passionate about Financial Independence and writes about Personal Finance and his journey to reach FI at 29, allowing him to retire at 30.